Protecting Where You Live in Northern NM
Whether you own an adobe near the Plaza or rent an apartment in Eldorado, the place you live is worth protecting the right way. We build home and renters coverage around Santa Fe realities like wildfire and hail, then bundle it with your auto to save.
Owners and Renters, Covered the Same Careful Way
If you own your home, you need protection that accounts for what it would truly cost to rebuild in today's market, plus the wildfire and hail risk that comes with living in Northern New Mexico. If you rent, you still need coverage for your belongings and your liability, because your landlord's policy does not protect either.
We treat both the same way: a real conversation with a Jacobs family member, honest advice in plain language, and a policy sized to your life rather than a template.
- Homeowners coverage priced to rebuild cost, not a guess
- Renters coverage for belongings and liability, often for less than you expect
- Wildfire and hail risk reviewed for your specific location
- Bundling with auto for a discount on every line
The Coverage Homeowners & Renters Need
Start with the policy that fits where you live today, then round it out. Each links to the full details.
Home Insurance
Customized homeowners coverage with real attention to wildfire and hail, the two biggest property risks in Northern New Mexico.
Explore Home InsuranceRenters Insurance
Affordable protection for your belongings and liability, whether you rent near the Plaza or out in Eldorado.
Explore Renters InsuranceWildfire Coverage
A focused review of your wildfire risk and the coverage gaps we see most often on homes across Northern New Mexico.
Explore Wildfire CoverageHigh-Value Personal Property
Scheduled coverage for jewelry, watches, and valuables inside your home that exceed standard policy limits.
Explore High-Value CoverageAuto Insurance
Bundle your home or renters policy with auto for a discount on each line and one point of contact for everything.
Explore Auto InsuranceLife Insurance
Once your home is protected, protect the people in it with term, whole, or universal life sized to your budget.
Explore Life InsuranceProtecting Your Home Before Fire Season
If you own a home in Northern New Mexico, this is the most useful section on this page. Wildfire mitigation is the work you do on your property to make the house survivable, and it is also what your insurance company will inspect and require. We handle both sides of that with our clients every week.
Work outward from the house in three zones
Defensible space is the buffer between your home and everything around it that can burn. Santa Fe County's Ready, Set, Go! program organizes it into zones measured out from the structure. Aim for at least 100 feet of treated space, and more if you are on a slope or in a heavily wooded area.
- Zone 1, the first 30 feet. Keep it leanest. Clear dead plants, dry grass, needles, and leaf litter, including off the roof and out of the gutters. Keep the first five feet around the foundation non-combustible — gravel or stone rather than bark mulch. Move woodpiles and propane tanks well away from the house, and clear out everything stored under decks and stairs.
- Zone 2, 30 to 100 feet. Thin trees and shrubs so their crowns are separated instead of forming a continuous canopy. Break up ladder fuels — the low limbs and brush that let a grass fire climb into the treetops. Prune lower branches up off the ground and keep dry grass mowed, in the cool of the morning rather than in afternoon wind.
- Zone 3, 100 to 200 feet. Keep thinning toward an open, healthy stand. Remove dead and dying trees, keep limbs clear of power lines, and keep the driveway wide and clear enough for a fire engine to get in and turn around.
Then harden the building itself. Most homes lost to wildfire are ignited by wind-driven embers arriving ahead of the fire, not by a wall of flame — so screen your vents, box in your eaves with non-combustible material, fit a spark arrestor on the chimney, screen the gutters, and keep the roof swept clear.
Your insurer inspects your property in the first 45 days — and can require the work
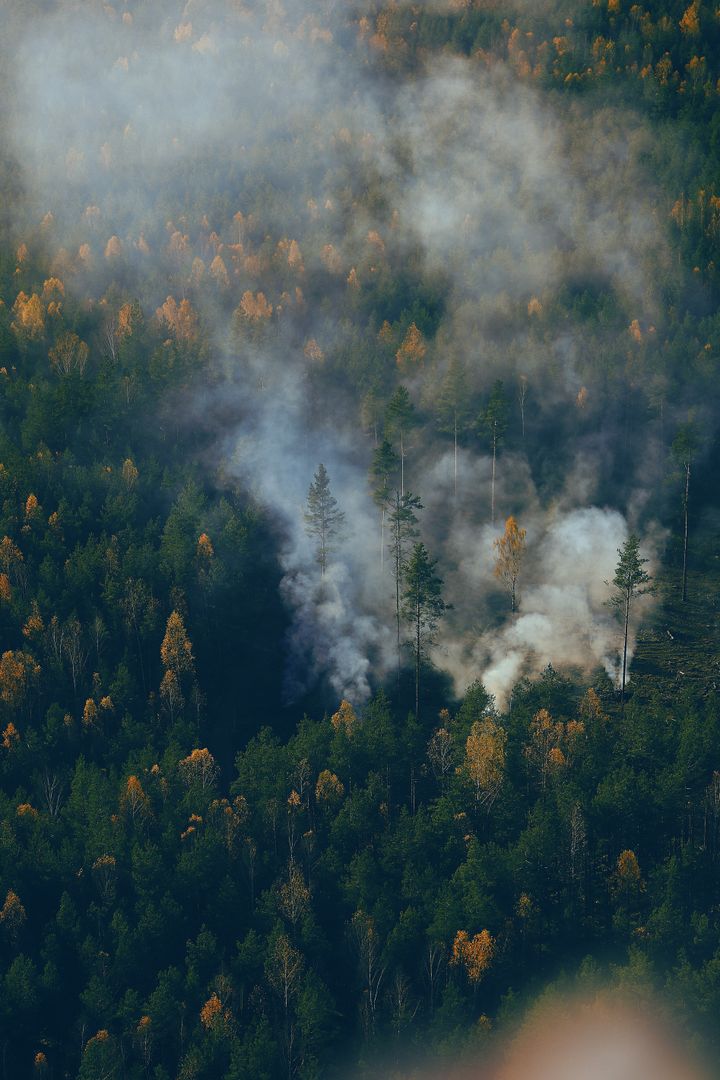
Binding a policy is not the end of underwriting. After a new home policy starts, the carrier typically reserves roughly the first 45 days to send an inspector out to photograph the property. If those photographs show wildfire hazards — brush against the walls, limbs over the roof, debris in the gutters, a woodpile on the deck — underwriting sends you a list of conditions to correct, with a deadline.
Completing that work is a condition of keeping the policy. If it is not done and documented in time, the carrier can cancel or non-renew, which leaves you replacing coverage on your home with a termination on record. It is entirely avoidable, and it is the single most common thing we help homeowners get ahead of.
One distinction worth knowing, because it confuses almost everyone: the fire department publishes the mitigation guidelines and will often assess your property for free, but on private land it advises rather than compels. Your insurance company is the one with real leverage, because it can make the work a condition of continuing to insure you. Do the work on the fire department's guidance, then document it for your insurer.
Coverage That Fits How You Live Here
A house or apartment in Northern New Mexico faces risks a generic policy overlooks. Here is what you get with a local family agency.
Wildfire Aware
We review your specific wildfire and hail exposure, not a statewide average.
Bundle & Save
Pair home or renters with auto and life for a discount on each policy.
A Real Neighbor
You talk to a Jacobs family member from quote to claim, never a call center.
Right-Sized Coverage
Insured to real rebuild and replacement cost, so you are neither over nor under-covered.