Home Insurance in Santa Fe, NM
Your home is likely the biggest thing you will ever own, and it deserves coverage built for where it actually sits. We write homeowners policies tuned to Northern New Mexico, including the wildfire and hail risks our neighbors know all too well. Backed by Allstate, serviced by a local family who picks up the phone.
Coverage Built for Northern New Mexico Homes
A homeowners policy is really four kinds of protection working together, and the right amount of each depends on your house, your belongings, and your life. We sit down with you and build a policy around all of it, from the walls and roof to the things inside and the liability that comes with owning property.
Every policy is backed by Allstate's national claims network, but you deal with a Jacobs family member from quote to claim, not a rotating call center that has never seen a Santa Fe winter.
What a home policy can include
- Dwelling coverage for the structure of your home
- Personal property for furniture, clothing, and belongings
- Personal liability if someone is hurt on your property
- Loss of use to cover living costs if your home is unlivable
- Wildfire and hail protection sized to Northern NM risk
- Other-structures coverage for casitas, sheds, and walls
Ways we help you save
- Multi-policy bundling. Pair home with auto, life, or an umbrella policy for a discount on each line.
- Protective-device credits. Smoke and burglar alarms, monitored systems, and defensible-space work can lower your premium.
- Right-sized deductibles. We balance premium against out-of-pocket cost instead of guessing at a number.
- Claims-free and loyalty savings. A clean history and staying with one agency can earn lower rates over time.
The Two Biggest Risks We Plan For
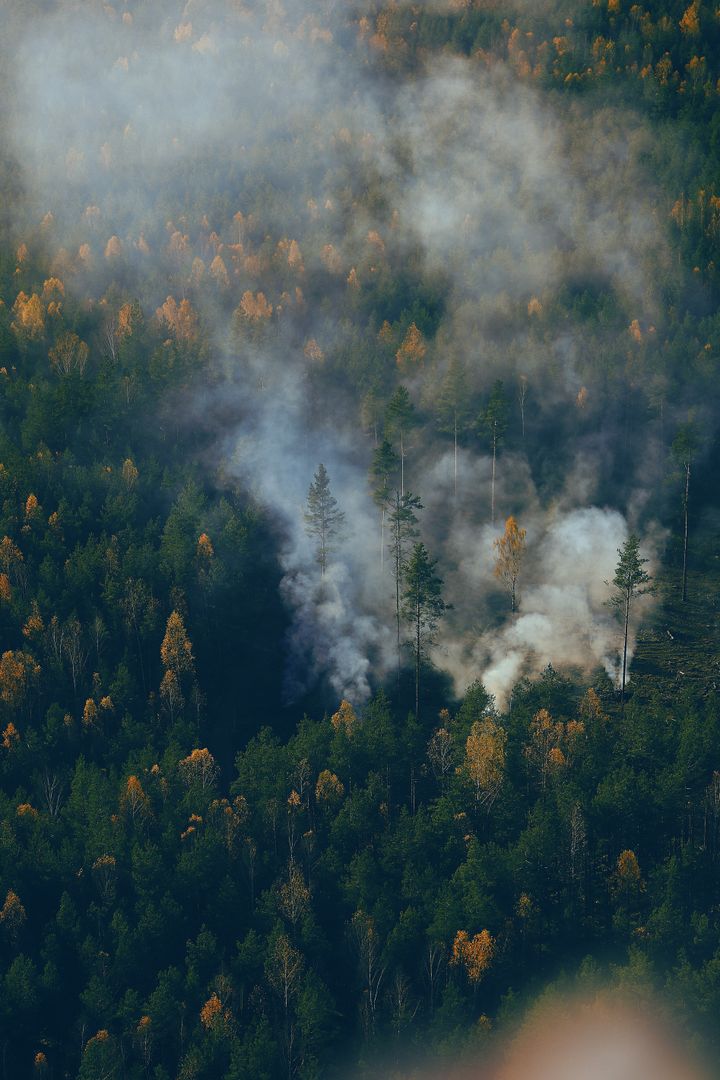
Wildfire and hail are the two losses we talk about most with Northern New Mexico homeowners, and for good reason. A single dry summer or one bad storm can do damage that a thin policy simply will not cover. We make sure your dwelling limit reflects what it would actually cost to rebuild here, not a number from a decade ago.
We also walk through the practical side: creating defensible space in zones out from the house, breaking up ladder fuels, clearing roof and gutter debris, screening vents against embers, and documenting your property before a loss so a claim goes as smoothly as it possibly can.
- Dwelling limits set to real local rebuild costs
- Wildfire and hail losses reviewed line by line
- Practical, zone-by-zone defensible space and home hardening guidance
- Help with the underwriting home inspection in your policy's first 45 days
Your New Policy Comes With an Inspection
This catches more Northern New Mexico homeowners off guard than anything else we deal with, so we want you to hear it from us first. Binding a home policy is not the end of underwriting. After the policy starts, the carrier typically reserves roughly the first 45 days to send an inspector out to photograph the property.
If those photographs show wildfire hazards — brush against the walls, limbs over the roof, needles in the gutters, a woodpile stacked on the deck, unscreened attic vents — underwriting sends you a list of conditions to correct, with a deadline. Completing that work is a condition of keeping the policy. If it is not done and documented in time, the carrier can cancel or non-renew, and replacing coverage afterward is harder than getting it right the first time.
Worth knowing, because it confuses nearly everyone: the fire department publishes the mitigation guidelines and will often assess your property for free, but on private land it advises rather than compels. Your insurance company is the one that can require the work, as a condition of continuing to insure you. We help our clients get ahead of this before the inspector ever shows up, and we read these notices every week.
More Than Four Walls and a Roof
The Dwelling
The structure itself, sized to rebuild here.
Your Belongings
Furniture, clothing, and everyday possessions.
Your Liability
Protection if someone is hurt on your property.
Adobe & Older Homes
Coverage that respects traditional construction.
Older Homes Need a Careful Eye
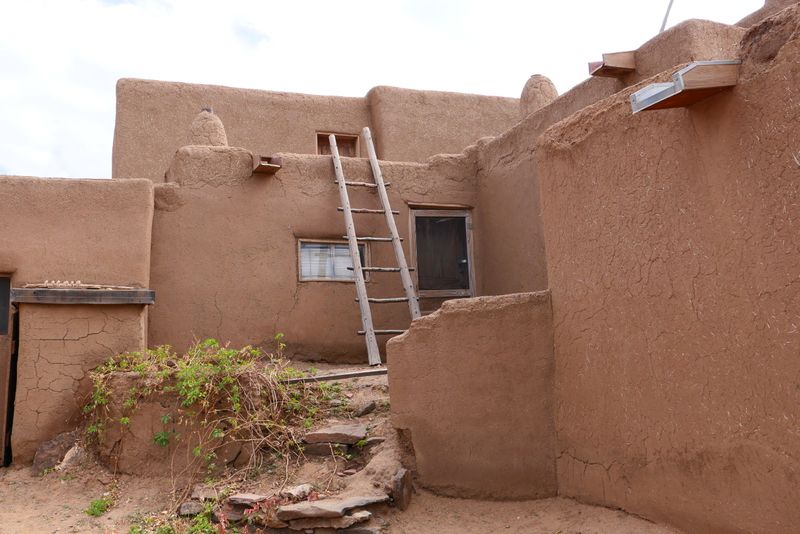
Adobe and older homes are part of what makes this region special, but they do not price out like a builder-grade house. Traditional materials, hand-plastered walls, and historic detail can cost more to repair than people expect. We help you understand the difference between replacement cost, which pays to rebuild with like materials, and actual cash value, which subtracts for age and wear.
For most homeowners here, replacement cost is the safer choice, and we will explain exactly what each option would mean for your home and your premium.
- Replacement cost vs actual cash value explained in plain language
- Limits that account for adobe and traditional construction
- A yearly review so your coverage keeps pace with rebuild costs